Diageo: the destocking is over; the de-rating may not be
North American inventories have normalised, but the market is right to question long-term spirits growth.
 James WhitlockUK Equities Analyst
Completed 8 Oct 2026, 14:30 CEST · First published 9 Oct 2026, 08:30 CEST
5 min read
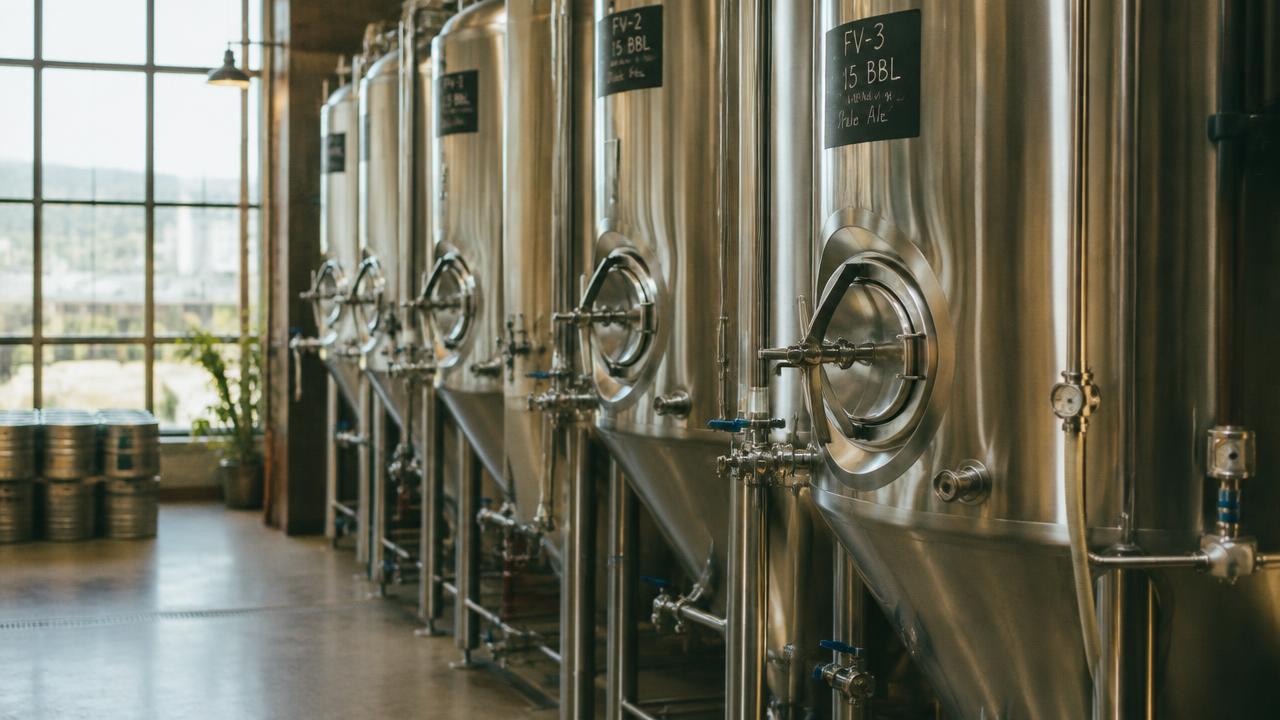
Diageo's first-quarter trading update confirmed what distributors have been telling us for months: the inventory overhang in US spirits has cleared. Organic net sales rose 1.8%.
Structural or cyclical?
The harder question is whether spirits consumption in developed markets will return to its pre-pandemic growth rate of 4% to 5% a year. Moderation among younger consumers and the spread of GLP-1 weight-loss drugs both argue for caution.
Valuation
At around 17 times forward earnings, the shares trade at their lowest multiple in more than a decade. Our fair value of 2,450p assumes organic growth of 3% to 4% over the medium term.
Rating
We rate the shares Hold. The balance sheet is stretched, with leverage of around 3 times, and we would like to see evidence that pricing is holding before becoming more constructive.
Disclosure
No position — covering the author and persons closely associated with them.
The author has no position in Diageo.
Other relationships: None.
This article is general information and the author's opinion. It is not investment advice and does not take into account your personal circumstances. Past performance is no guide to future returns. See our disclaimer.
Related
FTSE 100 closes at record as miners and banks rally
James Whitlock · 16 Oct 2026 · 2 min read
Shell: buybacks at this price are the best use of cash
James Whitlock · 13 Oct 2026 · 6 min read