Heineken: volumes are flat, but pricing power is not
The brewer is trading volume for price in Europe and Asia. That works until it does not; we see the shares as fairly valued.
 Eleanor VanceEuropean Equities Editor
Completed 13 Oct 2026, 14:30 CEST · First published 14 Oct 2026, 08:30 CEST
6 min read
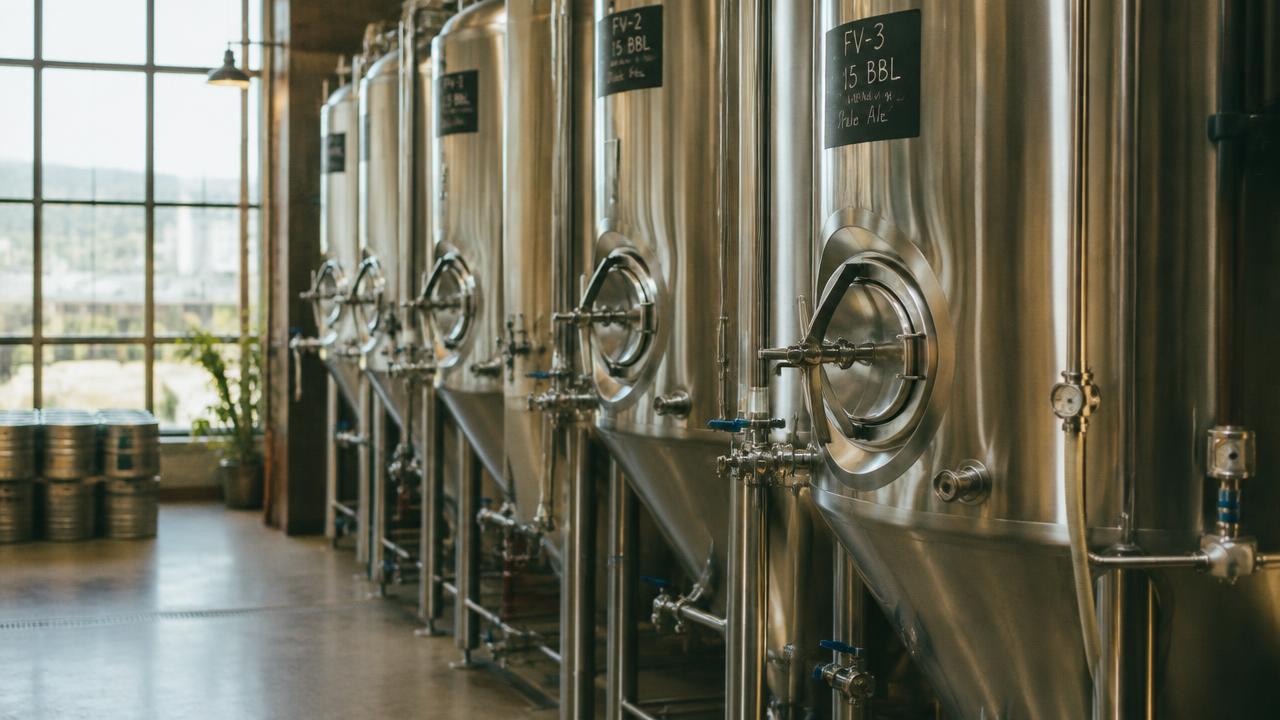
Heineken reported organic revenue growth of 4.2% for the first nine months, almost entirely from price and mix. Beer volumes were flat, with growth in Africa and Vietnam offset by declines in Europe.
The trade-off
Price-led growth has protected margins through two years of input-cost inflation. With barley and aluminium costs now falling, the question is how much of that pricing the company can keep. We expect a modest giveback in promotional intensity in 2027.
Balance sheet
Net debt to EBITDA of 2.4 times is comfortable for a business of this stability. The dividend payout of around 35% to 40% of net profit leaves room for continued buybacks.
Valuation and rating
At 16 times forward earnings, the shares trade in line with their European peers and at a discount to their own history. Our fair value of €88 implies limited upside from current levels. We maintain a Hold rating.
Disclosure
No position — covering the author and persons closely associated with them.
The author has no position in Heineken.
Other relationships: None.
This article is general information and the author's opinion. It is not investment advice and does not take into account your personal circumstances. Past performance is no guide to future returns. See our disclaimer.
Related
ECB trims deposit rate to 2.0% as euro-area growth stalls
Sofia Brandt · 17 Oct 2026 · 3 min read
ASML: a toll road with a cyclical surface
Eleanor Vance · 16 Oct 2026 · 7 min read
Siemens raises guidance on digital industries recovery
Eleanor Vance · 15 Oct 2026 · 2 min read
Why European dividend payers deserve a second look
Sofia Brandt · 12 Oct 2026 · 5 min read